We offer reports on the Argentine economic and financial situation, focused on key aspects such as the level of activity, fiscal accounts, inflation, interest rates and exchange rates.
Presentations
We make in-company presentations on the Argentine and international economic situation, adjusting to the client's needs.
Consultations
We are available for specific queries from our clients on current issues via phone or email.
Forecasting
We prepare detailed long-term economic forecasts and alternative scenarios for budgeting and decision making.
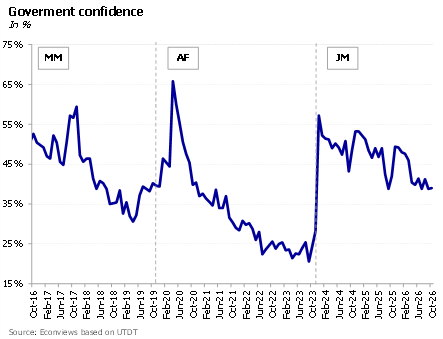
La discusión electoral empieza a ganar terreno en la agenda pública. La popularidad del oficialismo no es baja, pero en las encuestas se están viendo los costos que paga por una economía que no tiene fuerza en los grandes centros urbanos. El Índice de confianza en el gobierno elaborado por la UTDT está en valores mínimos para este gobierno y de acuerdo con consultoras privadas el porcentaje de desaprobación de la gestión es superior al de aprobación.
The global situation has become difficult, and Argentina is feeling the impact. International markets have been very volatile, but what stands out is that Argentine assets keep falling even on days when other markets recover, unlike the rest of the emerging markets. Country risk has reached 900 points, twice its level of three months ago. Ecuador, another high-risk borrower, has also had a hard time, but much less than Argentina: its country risk rose from 430 to 600 points over the same period.
La ola azul arrasa. El mercado reaccionó positivamente a la dura derrota de Trump en las elecciones, anticipando que puede haber menos irracionalidad o volatilidad en la política americana, como pasó con los aranceles o con la guerra. El Brent cayó debajo de US$ 95 después de que Vance culpara a la guerra por la derrota. Queda por ver si el conflicto con Irán depende de Trump o si es una política de Estado que Trump encarna de manera más excéntrica. Históricamente a los mercados les gusta un poder político dividido o en contrapeso, donde el Ejecutivo no tiene vía libre, aunque no está del todo claro si será mejor para las cuentas fiscales. Si las tasas descomprimen y se debilita el dólar, será una buena noticia para los emergentes y para Argentina, aunque pueden entrar menos dólares del petróleo.
We are still a year away from the presidential elections, but the anxiety about the outcome is already affecting investment decisions. The government’s slide in public opinion appears to have stopped, as the index of confidence in the government improved 0.8% in October. The mood appeared to be dominated by economic indicators that have been disappointing in recent months, especially regarding economic activity, employment and inflation. The government is now suffering from making promises that it has not been able to deliver, a fact that is generating concerns among investors and the population at large.
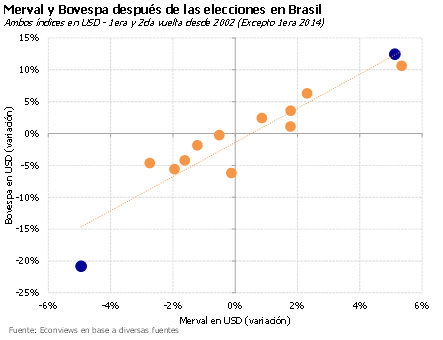
Efecto Lula. La remontada de Lula en Brasil les dio un nuevo golpe a los bonos y acciones argentinas y llevó al riesgo país a la zona de 750 puntos. Otros emisores de alto riesgo, como Ecuador y Egipto, también vienen sufriendo, lo que muestra un mercado más selectivo con el crédito emergente. En esa volteada, Argentina no tiene drivers sólidos para atraer nuevos compradores de cara a un año electoral que se percibe muy volátil y con resultado abierto. Esto pesa aun cuando las encuestas muestran la imagen del gobierno estable desde hace algunos meses, en niveles relativamente aceptables para esta altura del mandato.
Más rápido de lo que muchos economistas esperaban, el Gobierno va consolidando su objetivo de cerrar el año con déficit fiscal cero, mejora de las cuentas del Banco Central, y camino a la tasa de inflación de un dígito porcentual….
Graduate in Economics from the University of Buenos Aires and Ph.D. in Economics from Columbia University. Professor and researcher at the Di Tella University and academic advisor at FIEL
With vast experience as an advisor to multilateral organizations such as the IMF, the World Bank and the Inter-American Development Bank, as well as several Latin American countries, he held prominent roles in the financial sector, including the presidency of Banco Hipotecario S.A. and functions in the Ministry of Economy and the Central Bank of the Argentine Republic.
He was an Assistant Professor at the University of Maryland, and taught at institutions such as CEMA, Georgetown University, and Columbia University.
He is a columnist and author of numerous articles in international publications. Author of the book “The Argentine economic crisis, a history of adjustments and imbalances” with Sebastián Kiguel.
Graduate in Economics from the University of Buenos Aires and MSc in Economics from the University of Warwick (UK).
He was an economic consultant at the Inter-American Development Bank (IDB) and at Econviews. He also served as an advisor at the Ministry of Economy and the Ministry of Transport of Argentina.